<
Person typing on a laptop keyboard with a document open on the screen.
INVESTMENT MANAGEMENT

Your portfolio built for the work ahead

A portfolio is only as good as the obligations it can meet.

Investment conversations at this level can be messy: accounts scattered with no unifying logic, a portfolio built for growth when the need has shifted to income and protection, and holdings that look fine in isolation but were never coordinated against the family's actual obligations. The question is no longer about returns alone. That's where we come in.

Investment management at Arrowroot Family Office begins with what the money has to accomplish. Retirement income, gifting, philanthropy, liquidity for a transaction, and the unexpected all get mapped before the portfolio gets built around them. Because the same team runs the family's tax and estate work, every position is shaped with its tax and estate consequences in view.

Black and white grid of icons featuring speech bubbles, thumbs up, and chat symbols.

What coordinated investing makes possible

A portfolio with a job, not just a benchmark
Right-pointing arrow icon with a tail on a transparent background.
Tax built into every position
Right-pointing arrow icon with a tail on a transparent background.
Risk calibrated to the real picture
Right-pointing arrow icon with a tail on a transparent background.
One coherent portfolio across every account
Right-pointing arrow icon with a tail on a transparent background.

How the work happens

01
The introduction
02
The full picture
03
Building the framework
04
The day-to-day
05
Through the generations

01

The introduction

Investment relationships often begin through an introduction or after a transition puts new demands on the portfolio. The first conversation is about what the money needs to do and where the current approach falls short. You leave with a clear view of what coordinated management would change.
Close-up of a hand with an engagement ring holding an iPhone to the ear.

02

The full picture

Every account, entity, and holding comes into view. Custodian relationships, concentrations, cost basis, existing strategy, and the obligations the portfolio has to meet all get mapped. The result is one complete picture of the family's capital and what is asked of it.

Businessman in a gray suit talking on the phone and holding a leather folder.

03

Building the framework

An investment framework gets built around the family's obligations and coordinated with the tax and estate work. Allocation, risk posture, asset location, and liquidity planning get designed together rather than in isolation. You end with a portfolio strategy that reflects the full situation.

Person pointing at a laptop screen while another hand types on the keyboard indoors.

04

The day-to-day

Managing the portfolio is continuous work. Rebalancing, tax-loss harvesting, cash management, and need adjustments get handled by the team, with specialists pulled in when a decision crosses into tax or estate. The family directs the strategy rather than monitoring the mechanics.

Person in pinstripe suit and red polka dot tie holding a phone and notebook.

05

Through the generations

A portfolio has to serve the family across decades and transitions. The framework adapts as obligations shift, wealth transfers, and the next generation takes on a role in the decisions. The relationship continues so the strategy stays coherent as the family changes.

Plaid armchair with a dark textured cushion in a dimly lit cozy room with blurry background figures.

The advisor who builds the portfolio is the one managing it.

Investment management compounds over decades, and so should the relationship running it. The senior advisor who designs the portfolio is the one managing it through every market and every life change, not a name on the proposal who hands it to a desk. That continuity is what keeps the strategy connected to the family it serves.

Behind that advisor is the rest of the firm. Tax strategy, estate planning, and risk management all happen inside one team, so no position gets managed in isolation from its consequences. Concentrated client books keep the advisor close enough to the family to adjust the portfolio as the obligations behind it change.
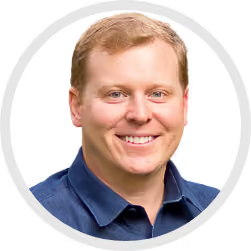
Redondo Beach, CA
Rob Santos
CEO

Rob works with founders, executives, and families navigating concentrated wealth, business exits, and generational planning. He founded Arrowroot in 2013 and leads the firm from Southern California.

CONNECT WITH Rob Santos
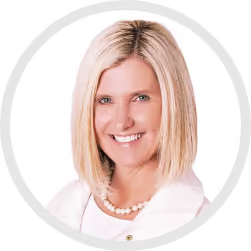
El Dorado Hills, CA
Cassandra Barry
Managing Director

Cassandra works with clients on retirement planning and Medicare strategy, with deep expertise in healthcare cost planning and the tradeoffs that shape later-life decisions. She is a licensed insurance agent with more than 12 years in financial services.

CONNECT WITH Cassandra Barry
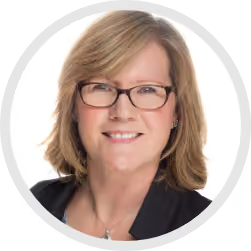
Gig Harbor, WA
Crystal McMahon, CFP®, EA
Managing Director

Crystal works with individuals, families, and business owners on financial planning, investment management, and tax strategy. She is a CFP® and IRS Enrolled Agent with over two decades of experience.

CONNECT WITH Crystal McMahon
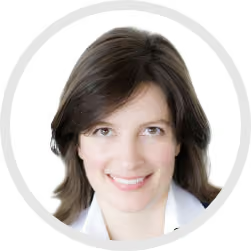
Denver, CO
Irene Apergis
COO

Irene oversees operations and regulatory compliance across the firm. She brings more than 22 years of financial services experience across investments, capital markets, operations, management, and sales.

CONNECT WITH Irene Apergis
Charlottesville, VA
Mark McCarron, CFP®, EA
Partner, Managing Director

Mark works with families and business owners on financial planning, portfolio management, and tax strategy, with a particular focus on cash flow and long-range projections. He is a CFP® and IRS Enrolled Agent.

CONNECT WITH Mark McCarron
Rochester Hills, MI
Diane Young, AIF®
Partner, Managing Director

Diane works with individuals, families, executives, and retirees on retirement planning, investment strategy, and long-term wealth management. She is an Accredited Investment Fiduciary® with over 30 years of experience.

CONNECT WITH Diane Young

How it all connects

Family Retreats

Business Succession

CFO Services

Next Generation Planning

Black reload or refresh icon with an arrow curving clockwise over a square.

Concierge Services

Charitable Giving

Investment Management

Risk Management

Tax Strategy

Estate Planning

Woman sitting on sandy beach watching a child standing near the water's edge with waves in background.

Family Retreats

Works in concert with governance and next generation planning, giving the structure a place to come alive in person. A retreat turns the framework into a conversation the whole family takes part in, away from the day-to-day. What surfaces there feeds directly into the decisions the family makes in the year that follows.

Explore Family Retreats
Grid of white dots arranged in eight rows and five columns on a black background.

Business Succession

Connects the operating company to the personal financial life it eventually funds. Succession is rarely a single event, and the years around it carry tax, estate, and liquidity decisions that compound. The framework coordinates the company side and the family side so the handoff happens on the family's terms.

Explore Business Succession
Grid of white dots arranged in eight rows and five columns on a black background.

CFO Services

Touches the family's businesses, cash flow, and reporting at the operational level. Daily financial oversight is where small issues either get caught early or quietly compound. The framework keeps the operating numbers connected to the family's longer financial picture.

Explore CFO Services
Grid of white dots arranged in eight rows and five columns on a black background.

Concierge Services

Carries the administrative weight that complex financial lives generate. Bill payment, document management, and the logistics of multiple properties and entities take real time and attention. The framework absorbs that load so the family directs the operation rather than running it.

Explore Concierge Services
Grid of white dots arranged in eight rows and five columns on a black background.

Investment Management

Anchored to the obligations the portfolio has to meet across the family's lifetime. Holdings fund retirement income, gifting, philanthropy, and the unexpected on schedules that match real life. Risk gets calibrated to the work the money has to do, and tax runs through every position.

Explore Investment Managemen
Grid of white dots arranged in eight rows and five columns on a black background.

Estate Planning

Touches every other practice the moment something changes. Estate structures only work if the tax, investment, and ownership positions behind them stay aligned. The framework keeps documents and entities current as the family and the assets shift.

Explore Estate Planning
Grid of white dots arranged in eight rows and five columns on a black background.

Tax Strategy

Threads through every investment decision, every entity, and every estate document. Tax efficiency at this level depends on timing and coordination as much as the individual choice. The framework is built so the math holds up across decades rather than a single filing year.

Explore Tax Strategy
Grid of white dots arranged in eight rows and five columns on a black background.

Risk Management

Protects what the family has built when something goes wrong. Coverage and exposure get sized to the real picture across businesses, properties, dependents, and estate liquidity. The framework keeps protection matched to the situation as obligations change.

Explore Risk Management
Grid of white dots arranged in eight rows and five columns on a black background.

Charitable Giving

Connects the family's philanthropy to its tax position, its estate plan, and the next generation. The structures built around giving outlast the impulses that began it. The framework keeps the giving coordinated with everything else rather than left to the side.

Explore Charitable Giving
Grid of white dots arranged in eight rows and five columns on a black background.

Next Generation Planning

Pairs with family governance and estate planning to prepare the people who will inherit. Readiness is built over years, through gradual involvement rather than a single handoff. The framework brings the next generation in on a cadence that respects where they are.

Explore Next Generation Planning
Grid of white dots arranged in eight rows and five columns on a black background.

Start a conversation

Most of our relationships begin with an introduction. If you've been sent our way, or you've simply decided it's time, this is where to reach us.

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.